Key Points
Broadcom expects AI chip revenue to double over the next couple of fiscal years, driven by its impressive clientele.
The company’s custom AI chip customers are on track to ramp up the deployment of Broadcom chips.
Broadcom offers a mix of growth and value compared to peers such as Nvidia and AMD.
- 10 stocks we like better than Broadcom ›
Nvidia (NASDAQ: NVDA) and Advanced Micro Devices are among the leading designers of chips used in artificial intelligence (AI) data centers, which helps explain why both companies have been posting healthy financial growth.
The graphics processing units (GPUs) and server central processing units (CPUs) designed by both companies are deployed in AI data centers to perform tasks such as training AI models, running inference, and creating and deploying AI agents. Both semiconductor stocks have delivered incredible returns to investors in recent years, and they can keep flying higher over the long run amid the huge investments in AI infrastructure.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, Broadcom (NASDAQ: AVGO) is quietly giving Nvidia and AMD serious competition in AI chips. Let’s take a closer look at Broadcom’s AI business and find out why it is becoming a powerhouse in the AI semiconductor space.
Image source: The Motley Fool.
Broadcom is capitalizing on the fast-growing custom AI chip demand
Broadcom designs application-specific integrated circuits (ASICs), which means it addresses a different niche than AMD and Nvidia, which design server CPUs and GPUs for AI data centers. The demand for these custom AI processors has taken off due to their cost efficiency, especially in inference.
It is estimated that custom AI chips can reduce inference costs by 40% to 60% compared to GPUs. Not surprisingly, major hyperscalers and AI companies have been focusing on developing in-house chips to lower operating costs. Specifically, Broadcom has six core customers for its custom AI chips, as the company noted on its June earnings call. These include Alphabet‘s Google, Meta Platforms, OpenAI, and Anthropic.
These customers are deploying Broadcom’s custom silicon in large volumes. This explains why Broadcom’s custom AI processor shipments shot up by 3.5x year over year in the third quarter of fiscal 2026 (which ended on Aug. 2). This massive jump led to a 221% year-over-year increase in Broadcom’s AI semiconductor revenue last quarter to $16.7 billion. Custom silicon accounted for nearly three-fourths of the company’s AI revenue.
Looking ahead, Broadcom sees its key customers ramping up the deployment of custom AI processors. As a result, Broadcom sees its AI revenue increasing at a stronger rate of 236% year over year in the current quarter to $21.7 billion. The company is on track to deliver $58 billion in AI revenue in fiscal 2026, ahead of its original expectation of $56 billion.
Importantly, the incredible growth is poised to continue beyond fiscal 2026, as Broadcom is witnessing “exponential growth in demand” for custom chips from its AI customers. For instance, Broadcom will deploy 1 gigawatt of custom AI chips for Anthropic in 2026, followed by 5 gigawatts in 2027 and 10 gigawatts in 2028. It expects Google and OpenAI to accelerate custom silicon deployments as well.
As a result, Broadcom is confident it will generate $115 billion in AI revenue in fiscal 2027, followed by $230 billion in fiscal 2028. The important part is that Broadcom has secured the supply needed to support this outstanding AI revenue growth over the next couple of years.
What’s worth noting is that Broadcom’s AI business is now much larger than AMD’s. Broadcom’s $58 billion fiscal 2026 AI revenue estimate is well above the $25 billion revenue run rate of AMD’s data center business in 2026 (it has generated $12.5 billion in data center revenue in the first half of 2026). Meanwhile, the fiscal 2028 forecast of $230 billion suggests that Broadcom will firmly position itself as the second-most important company in AI chips.
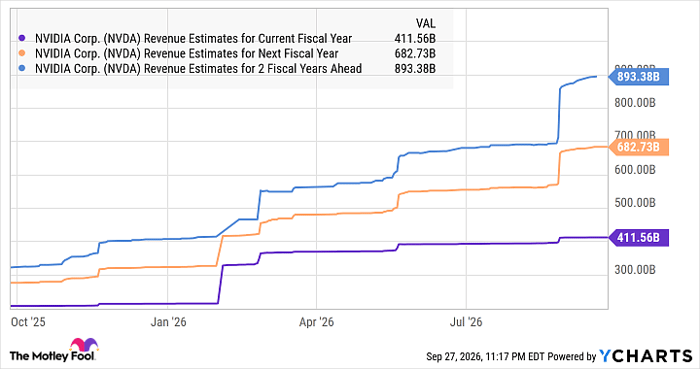
Nvidia, for example, has clocked $164 billion in data center revenue in the first six months of fiscal 2027. That translates into an annual run rate of almost $330 billion. Nvidia expects a 70% increase in its top line in fiscal 2028. As Nvidia derives over 90% of its revenue from data center chips, it is on track to see a significant revenue bump from this segment.
Data by YCharts
The chart above indicates that Nvidia’s data center revenue could exceed $800 billion in fiscal 2028 (assuming it continues to derive 90% of its overall revenue from this segment). So Nvidia will remain an AI powerhouse. But Broadcom predicts a stronger increase in AI revenue, so it may eventually give Nvidia a run for its money in the AI chip market.
Broadcom’s valuation makes it a better buy than Nvidia and AMD
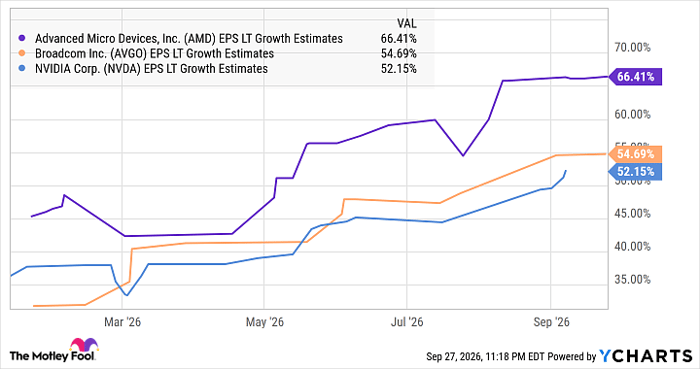
Nvidia, AMD, and Broadcom are expected to clock impressive growth in their earnings per share (EPS) over the long run.
Data by YCharts
AMD is expected to deliver the fastest EPS growth, followed by Broadcom and Nvidia. However, investors looking to buy an AI stock that offers a mix of value and growth can consider Broadcom. That’s because Broadcom trades at just 19 times forward earnings, which is lower than Nvidia’s forward earnings multiple of 25 and AMD’s multiple of 39.
All this makes Broadcom a top AI chip stock to buy and hold over the long run, as its accelerating growth and cheaper valuation could help it deliver bigger gains than Nvidia and AMD.
Should you buy stock in Broadcom right now?
Before you buy stock in Broadcom, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Broadcom wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $383,680!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,382,954!*
Now, it’s worth noting Stock Advisor’s total average return is 937% — a market-crushing outperformance compared to 214% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of September 28, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices, Alphabet, Broadcom, Meta Platforms, and Nvidia. The Motley Fool has a disclosure policy.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.